Does Pet Insurance Cover French Bulldog IVDD? Waiting Periods & Traps (2026)
Intervertebral Disc Disease (IVDD) is the single most catastrophic medical expense a French Bulldog owner can face. In our breakdown of French Bulldog spinal surgery costs, we revealed that advanced imaging and surgical intervention routinely exceed $8,000 to $12,000. For most owners, private pet insurance is the only safeguard against economic euthanasia.
However, pet insurance coverage for spinal conditions is neither automatic nor unconditional. Underwriters enforce strict waiting periods, pre-existing clauses, and breed-specific exclusions to limit exposure. Understanding policy mechanics before clinical signs appear is critical; for medical symptoms and disease staging, review our comprehensive French Bulldog IVDD guide.
1. Does Pet Insurance Cover IVDD?
The short answer is yes, but only under a strictly defined timeline.
Every major pet insurance provider covers diagnostics (MRI, CT scans), specialized neurosurgery (hemilaminectomy), and post-operative rehabilitation for IVDD—provided the policy is active before the dog displays any clinical symptoms of spinal distress.
Pet insurance operates strictly against unforeseen future risks. It never covers pre-existing conditions. Because chondrodystrophic breeds like French Bulldogs possess genetically mutated intervertebral discs prone to premature calcification, underwriters inspect spinal claims with intense diagnostic scrutiny.
2. Three Critical Policy Traps That Disqualify IVDD Claims
Spinal claim denials rarely stem from vague fine print denying “IVDD” by name. Instead, denials occur because of three specific procedural exclusions:
Trap 1: Orthopedic Waiting Periods (14 Days vs. 6 Months)
All pet insurance policies feature a waiting period after enrollment during which coverage is inactive:
- Standard Illness Window: Most underwriters enforce a 14-day window for medical conditions.
- Extended Orthopedic/Spinal Window: Several prominent underwriters classify IVDD, cruciate tears, and disc disorders under special orthopedic categories requiring an extended 6-month waiting period.
If your Frenchie stumbles, displays a roached back, or shows hind-limb weakness on Day 45 of a 6-month orthopedic window, all spinal treatments for that incident—and all subsequent complications—are permanently excluded for the dog’s lifetime.
Trap 2: The “Vague Medical Record” Exclusion
When you file an IVDD claim, adjusters request your dog’s complete veterinary history from every clinic visited since adoption. Adjusters scrutinize clinical progress notes for early indicators:
- “Dog hesitated before jumping off examination bench.”
- “Mild spinal sensitivity noted during routine physical exam.”
- “Puppy prescribed NSAIDs for minor neck soreness.”
Even if these notes never resulted in an official IVDD diagnosis at the time, adjusters classify them as pre-existing clinical indicators. Any subsequent herniation will be rejected as an extension of that prior undocumented event.
Trap 3: Bilateral & Contiguous Disc Exclusions
A dog’s spine contains dozens of individual discs. If your dog undergoes surgery for an L2–L3 disc rupture and later herniates the adjacent T13–L1 disc two years down the road, coverage depends entirely on contract wording:
- Favorable Underwriting: Evaluates each disc rupture as an independent medical event once the dog completes recovery.
- Restrictive Underwriting: Classifies the entire vertebral column as a single contiguous anatomical system, treating any future disc disease anywhere along the spine as a related pre-existing condition.
3. Real-World IVDD Financial Breakdown: Out-of-Pocket vs. Insured
Spinal crises require emergency referral to veterinary neurology centers. The financial difference between an uninsured incident and an active 90% reimbursement policy is significant:
| Diagnostic & Treatment Item | Uninsured Total Cost | Out-of-Pocket with 90% Policy ($250 Deductible) |
|---|---|---|
| Emergency ER Visit & Neurological Exam | $250 – $500 | $25 – $50 |
| Spinal MRI / CT Scan under Anesthesia | $2,500 – $4,000 | $250 – $400 |
| Hemilaminectomy / Surgical Decompression | $5,000 – $7,500 | $500 – $750 |
| Hospitalization & Post-Op ICU Care (3–5 Days) | $1,500 – $3,000 | $150 – $300 |
| Rehabilitation (Hydrotherapy & Laser Sessions) | $1,200 – $2,000 | $120 – $200 |
| Total Estimated Expense | $10,450 – $17,000 | $1,045 – $1,700 + $250 Deductible |
To maintain baseline vitality and reduce secondary structural strain, consult our foundational French Bulldog health guide.
4. How Leading Pet Insurers Treat Frenchie Spinal Conditions
Underwriters evaluate French Bulldog spinal risks under widely different criteria:
- Trupanion: Imposes no extended orthopedic waiting period; spinal coverage begins immediately after standard illness waiting periods clear. Employs a per-condition lifetime deductible, providing long-term cost benefits for chronic spinal management.
- Lemonade: Offers competitive entry-level premiums, but enforces strict medical chart audits and standard orthopedic exclusion windows unless an explicit medical exam waiver is submitted.
- Embrace: Enforces a 6-month orthopedic waiting period by default, but allows owners to submit an Orthopedic Exam Waiver completed by a vet within the first 14 days to unlock immediate spinal coverage.
Selecting the right plan requires aligning policy clauses with your dog’s age and past clinical documentation. For complete rankings and detailed policy analysis, explore our independent breakdown of the best pet insurance for French Bulldogs.
5. Strategic Rules for Insuring a Frenchie Against IVDD
- Enroll Prior to Age One: Over 70% of canine disc herniations occur between 3 and 7 years of age. Securing a policy during puppyhood prevents incidental veterinary chart notes from being leveraged as pre-existing conditions.
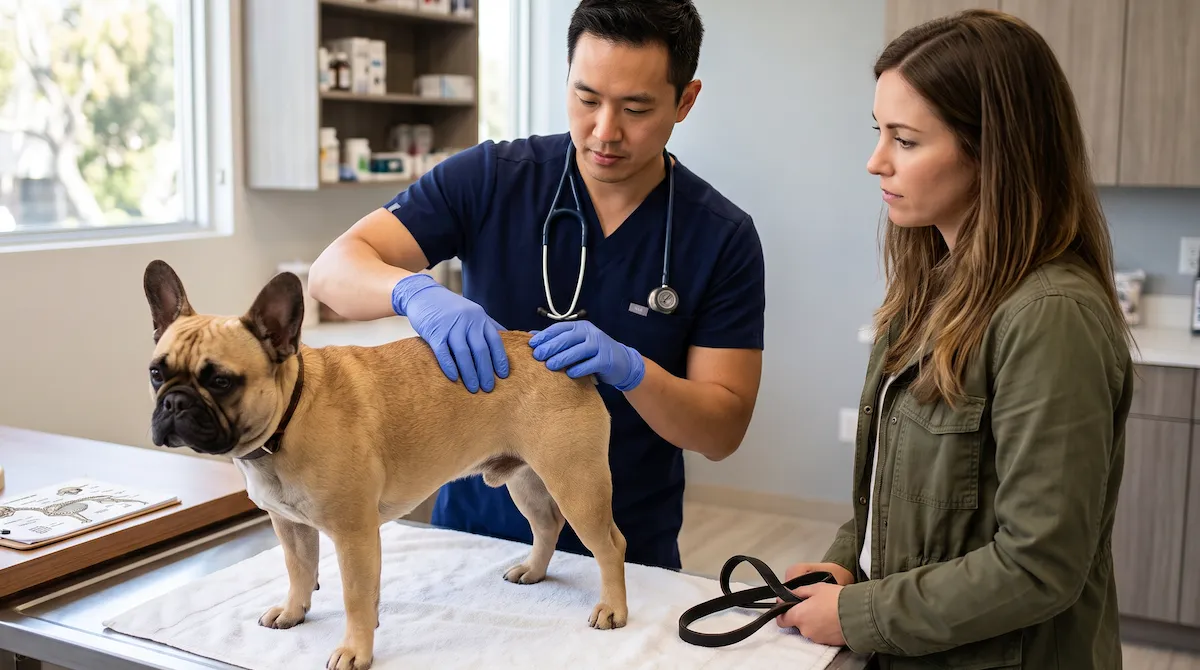
- Establish a Clean Medical Baseline Early: Book a wellness check when your dog is completely symptom-free. Request that the veterinarian explicitly writes: “Spine palpates normally; no spinal pain, stiffness, or neurological deficits detected.”
- Select at Least 80% to 90% Reimbursement with High Payout Limits: Because neurosurgical interventions frequently surpass $10,000, policies capped at $5,000 annually leave owners exposed to heavy out-of-pocket balances. Choose plans with at least $10,000 to unlimited annual payout limits.